Your Salary Is Not the Only Income That Counts for a Mortgage and Here Is What Else Qualifies
The Question That Changes Everything About What You Can Borrow
Most mortgage conversations start with the same question. What is your salary? Kendra LaManna at New American Funding wants to start with a better one. What income do you have and how much of it can actually be used to qualify?
Those two questions produce very different answers and very different outcomes for buyers who have been told they do not qualify for as much as they actually need.
The Borrowers Who Are Leaving Qualifying Income on the Table
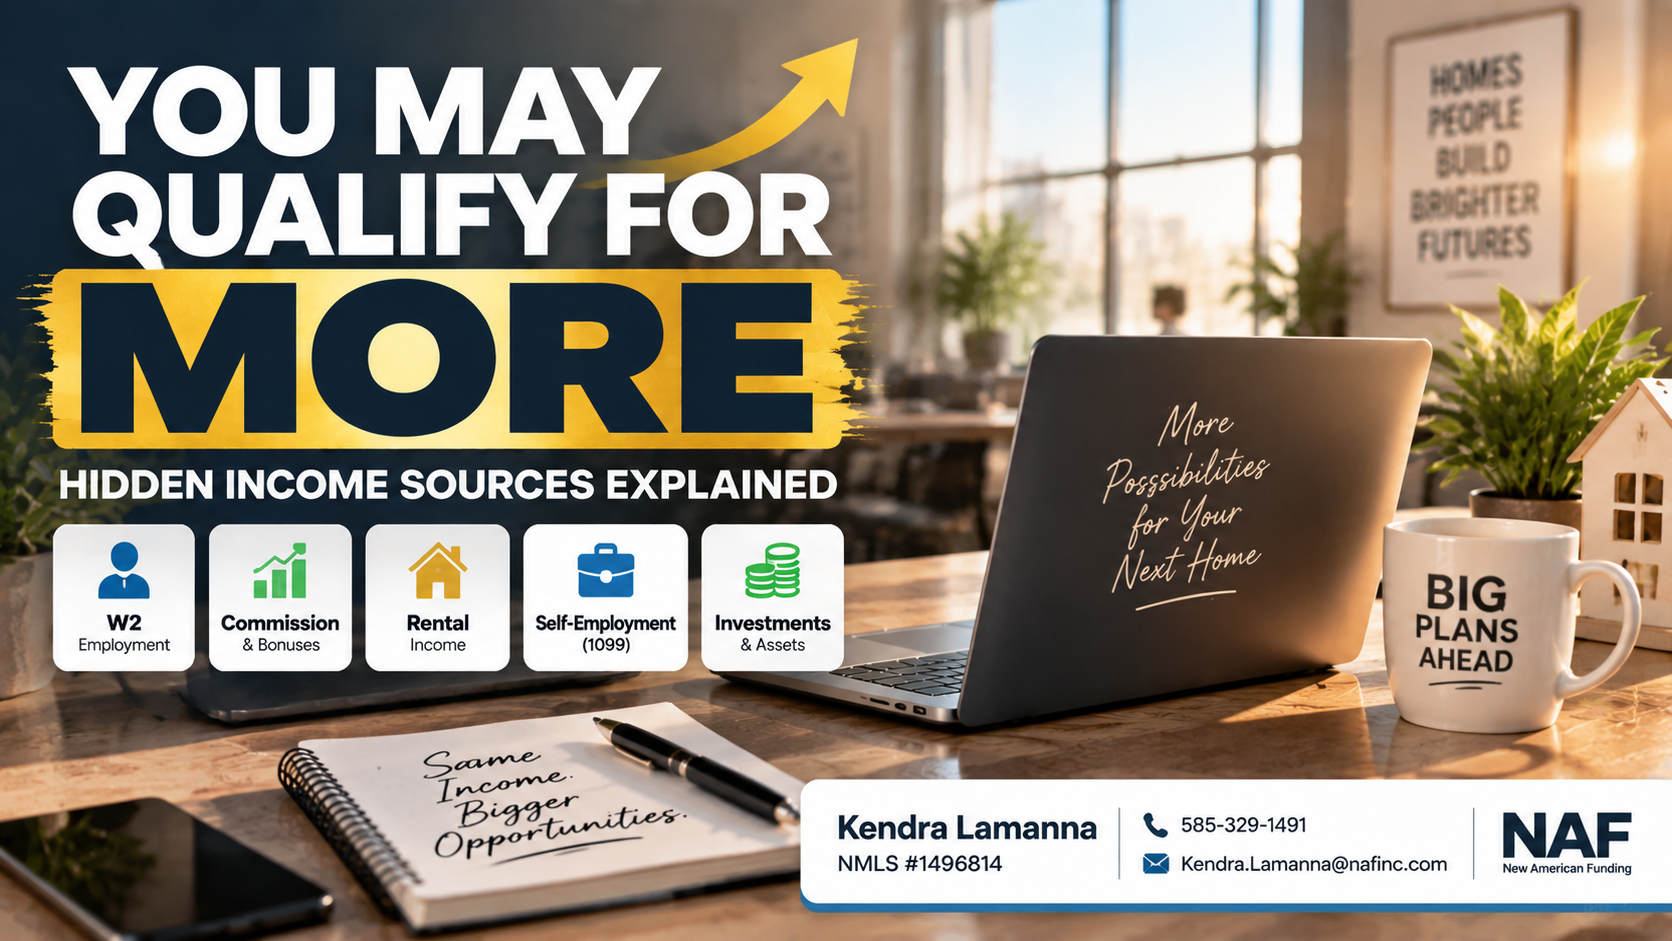
The W-2 employee who also earns commission and bonuses. The bonus history can often be averaged and added to the base salary. The commission income that shows up inconsistently on a pay stub can be documented and counted when the history supports it. These borrowers are frequently qualifying on base salary alone when their total compensation picture would support a meaningfully higher loan amount.
The self-employed business owner who also collects rent from investment properties. The business income and the rental income are two separate streams. Both may be eligible depending on documentation and loan program. Using only one while ignoring the other leaves real qualifying power unused.
The 1099 contractor with liquid assets or investment accounts producing dividends and interest. Asset depletion programs can convert a portion of those holdings into a calculated monthly income figure for qualification purposes. The money is there. The right program just needs to see it the right way.
The borrower purchasing with a co-borrower whose income profile looks completely different. A W-2 employee and a self-employed partner. A salaried worker and a freelancer. Combining income streams from two people with two different documentation paths is exactly where understanding the guidelines produces better outcomes than defaulting to the most conservative approach.
What the Alternative Programs Cover
For borrowers whose income does not fit the conventional documentation model alternative programs can evaluate twelve or twenty-four months of bank statement deposits as a measure of actual cash flow. A CPA-prepared profit and loss statement. The rental income a property generates rather than the borrower's personal income through DSCR qualification. Each of these replaces the tax return as the primary income document when the tax return does not tell the real story.
The Bottom Line
You may not need to earn more to increase your buying power. You may just need someone who knows where to look for the income you already have.
Kendra LaManna is with New American Funding NMLS 1496814. You find the home and she will find the loan. Call or text 585-329-1491 or email [email protected].
Sources
ConsumerFinancialProtectionBureau.gov
FannieMae.com
MortgageNewsDaily.com
NationalMortgageProfessional.com
Investopedia.com