Fannie Mae and Freddie Mac Updated Condo Requirements and Here Is What Every Buyer and Owner Needs to Know
The Condo Financing Reality Most Buyers Do Not Realize Until It Is Too Late
When you buy a condo your lender is not just approving you for the mortgage. They are also approving the condo project itself. That is the part most buyers never hear about until a problem surfaces two weeks before closing and suddenly a deal that felt done is in serious jeopardy.
Kendra LaManna at New American Funding wants buyers, sellers, and current condo owners to understand what has changed and why it matters before they find out the hard way.
What Fannie Mae and Freddie Mac Are Now Focused On
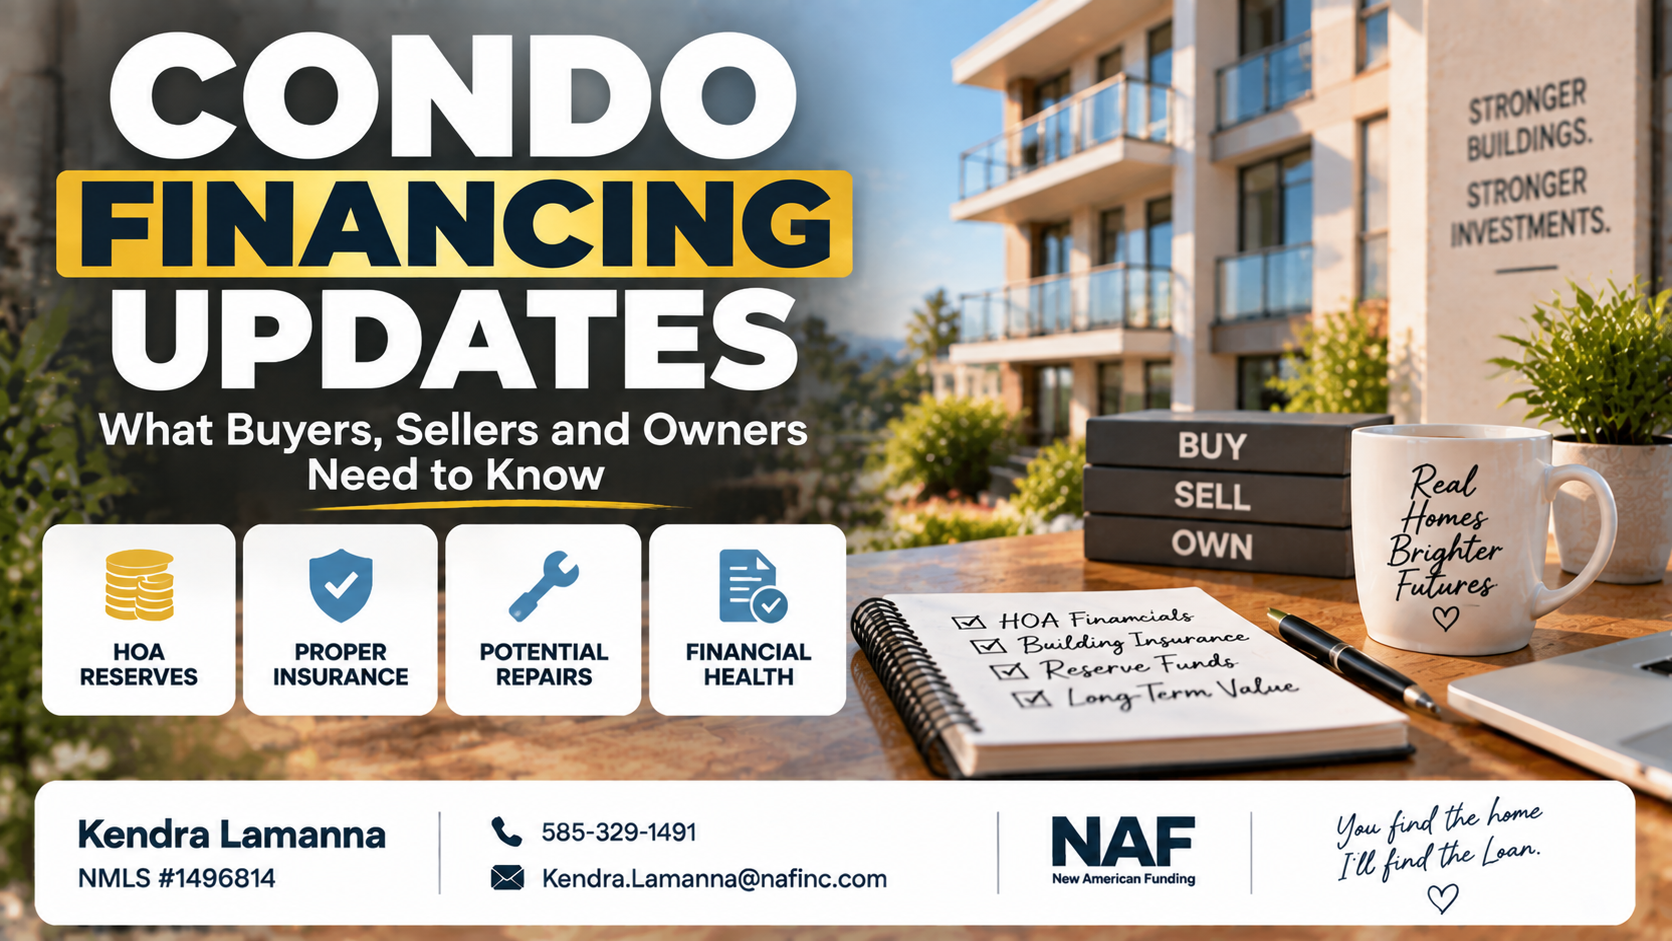
The updates to conventional condo requirements put significantly more emphasis on the financial and physical health of the building and the homeowners association behind it. Lenders are now looking more closely at several specific factors.
Reserve funding is one of the primary areas of scrutiny. Does the HOA have adequate reserves to handle major repairs and ongoing maintenance needs? An underfunded reserve is a red flag that signals a community that may be one significant expense away from a special assessment or deferred maintenance that affects property values across the building.
Insurance coverage is reviewed to confirm that the building is properly insured at adequate levels for its size, construction type, and location. Gaps in coverage can make a project ineligible for conventional financing regardless of how perfect an individual unit looks.
Pending or active special assessments are examined because they represent financial obligations that buyers may be inheriting. A major assessment for a roof replacement, structural repair, or elevator upgrade affects both affordability and the overall financial health of the community.
Long-term maintenance planning and the association's financial capacity to sustain the property are evaluated because a condo that is well-maintained today but has no financial plan for tomorrow is a different risk than one with a healthy reserve and a proactive board.
Why These Changes Are Actually a Good Thing
The updates are designed to protect homeowners and their investments by ensuring that the communities they are buying into are financially stable and physically sound. A condo that looks perfect on the interior tour can have a homeowners association that is struggling financially or managing deferred maintenance that will eventually require significant spending. The new requirements surface those issues earlier rather than letting buyers discover them after closing when it is too late to make a different decision.
What This Means Depending on Your Situation
For buyers the most important takeaway is to not wait until two weeks before closing to start the project approval process. Identifying HOA documentation issues, reserve fund shortfalls, or insurance gaps early in the transaction gives everyone time to address problems or make informed decisions about whether to proceed. Start the condo review process as early as possible.
For sellers understanding the financial status of your condo association before an offer comes in removes the risk of a deal falling apart at the project review stage. If there are known issues with reserves or pending assessments knowing about them early allows you to set realistic expectations and price accordingly.
For current owners this is a reminder to pay attention to what is happening in your HOA. Attend meetings. Review the financials. Understand the reserve fund status and the insurance coverage. The financial health of your association affects the market value and the financability of every unit in the building including yours.
The Better Question to Ask When Buying a Condo
Kendra frames the shift in thinking this way. Instead of only asking can I afford this condo also ask what is the well-being of this property. What is the physical health and the long-term financial stability of this community. Both questions matter and the answer to the second one determines whether conventional financing is even possible regardless of your personal qualifications.
Kendra LaManna is with New American Funding NMLS 1496814. You find the home and she will find the loan. Call or text 585-329-1491 or email [email protected].
Sources
FannieMae.com
FreddieMac.com
ConsumerFinancialProtectionBureau.gov
MortgageNewsDaily.com
HUD.gov