A Fixed Rate Mortgage Does Not Mean Your Monthly Payment Can Never Change and Here Is Why
The Misconception That Catches Homeowners Off Guard Every Year
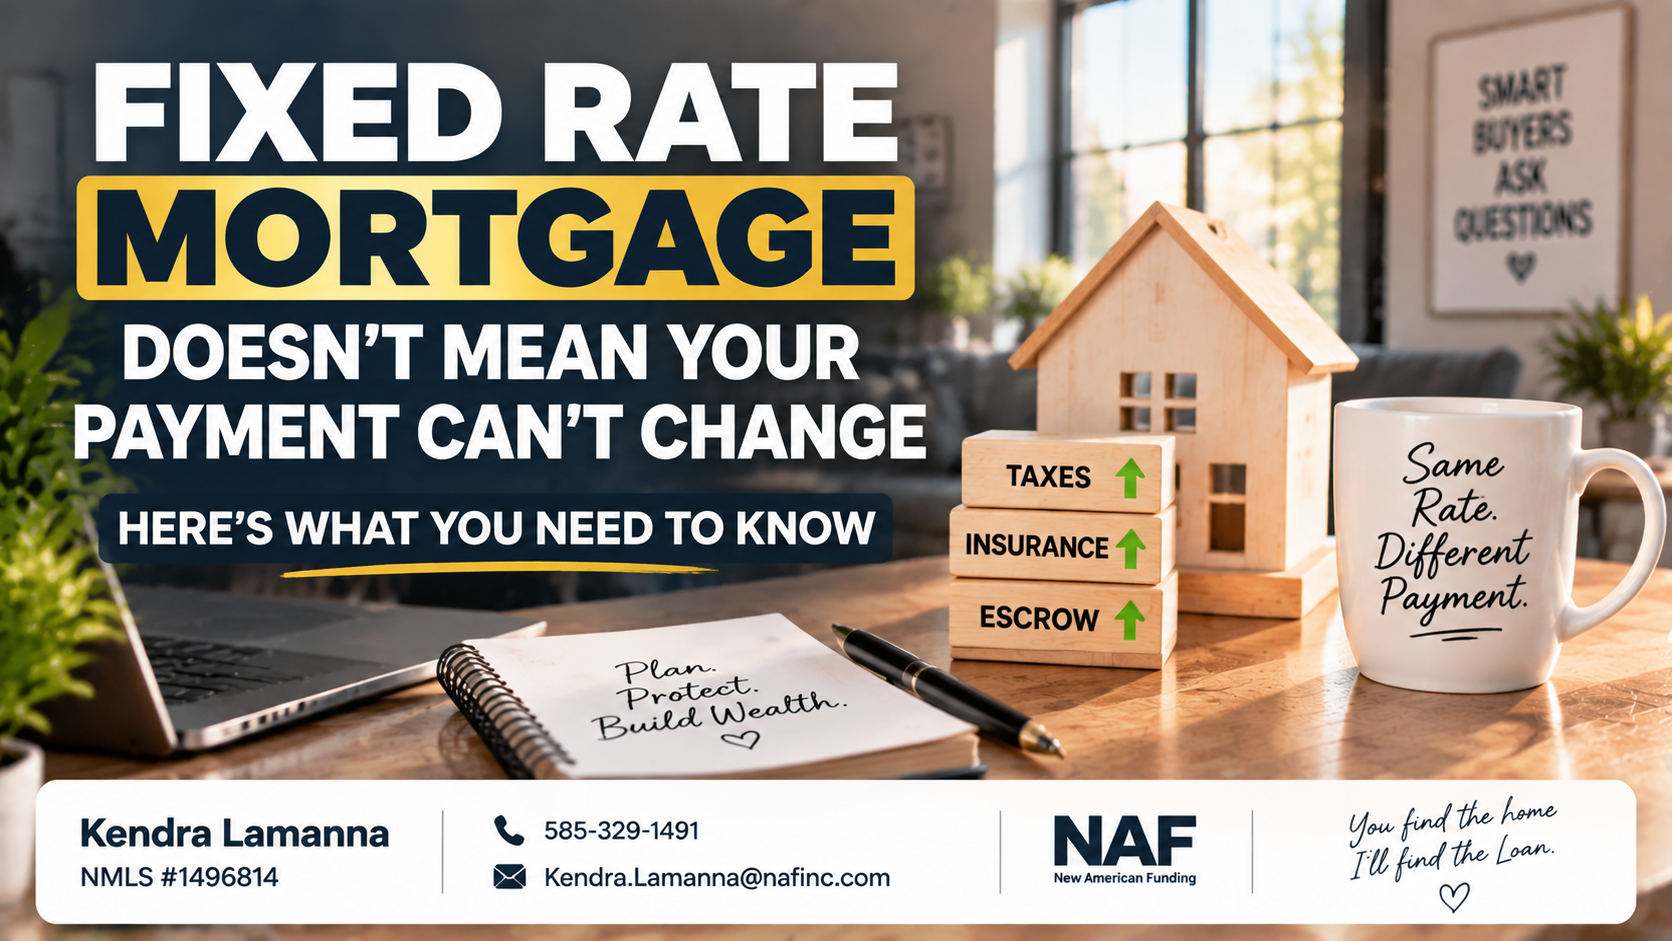
A fixed rate mortgage means your interest rate is locked for the life of the loan. What it does not mean is that your monthly payment is permanently fixed at the number you saw on closing day. Kendra LaManna at New American Funding hears this misconception regularly and wants to clear it up before it catches anyone off guard.
What Actually Stays Fixed and What Does Not
The principal and interest portion of your mortgage payment is fixed. That number does not change based on market conditions, Fed decisions, or anything else. If you locked a thirty-year fixed rate at six and a half percent your principal and interest payment is the same in year fifteen as it was in month one.
But for most borrowers the monthly mortgage payment includes more than principal and interest. If your lender collects taxes and insurance through an escrow account those amounts are collected alongside the principal and interest as part of the same monthly payment. And those amounts are not fixed.
Three Reasons Your Payment Can Increase Without Your Rate Changing
Property taxes go up. Local governments reassess property values and adjust tax rates and when they do the escrow requirement increases to cover the higher annual tax bill. That increase flows directly into the monthly payment.
Homeowners insurance premiums go up. Insurance carriers raise rates based on claims history, weather events, market conditions, and the replacement cost of materials. When the premium increases at renewal the escrow requirement adjusts accordingly.
Escrow shortfalls catch homeowners off guard. If the escrow account collected less than it actually needed to pay taxes and insurance over the prior year the servicer will identify a shortage at the annual escrow analysis. That shortage typically gets spread across the next twelve months as a slightly higher monthly payment until the account is back in balance.
None of these changes touch the interest rate. They reflect the changing cost of owning the home rather than a change in the loan itself.
What to Do When the Payment Increases
As Kendra LaManna explains reviewing the annual escrow analysis is the first step. Understanding exactly why the payment changed and whether it is a tax increase, an insurance increase, or a shortage correction helps determine the right response.
Comparing homeowners insurance options at renewal is worth doing every year or two. Coverage requirements stay the same but premiums vary across carriers and finding equivalent coverage at a lower premium reduces the escrow requirement and the monthly payment.
Challenging a property tax assessment is an option many homeowners do not know they have. If the assessed value of the property seems inaccurate a formal appeal can produce a reduction that flows into lower tax bills for years going forward.
Making Every Dollar Work for You
Whether you are buying your first home or moving up the goal is the same. Build wealth, protect it, and keep the process as stress-free as possible. Understanding what drives your monthly payment and what you can actually do about it when it changes is part of that.
Follow Kendra LaManna for more straightforward guidance that keeps your costs minimal. NMLS 1496814. Call or text 585-329-1491 or email [email protected].
Sources
ConsumerFinancialProtectionBureau.gov
FannieMae.com
MortgageNewsDaily.com
Investopedia.com
BankRate.com