Your Local Mortgage Lender
Located in Charlotte, North Carolina
Personalized Mortgage Experience
Kendra Lamanna offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Charlotte, North Carolina.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Want To Get Approved For A HELOC?
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
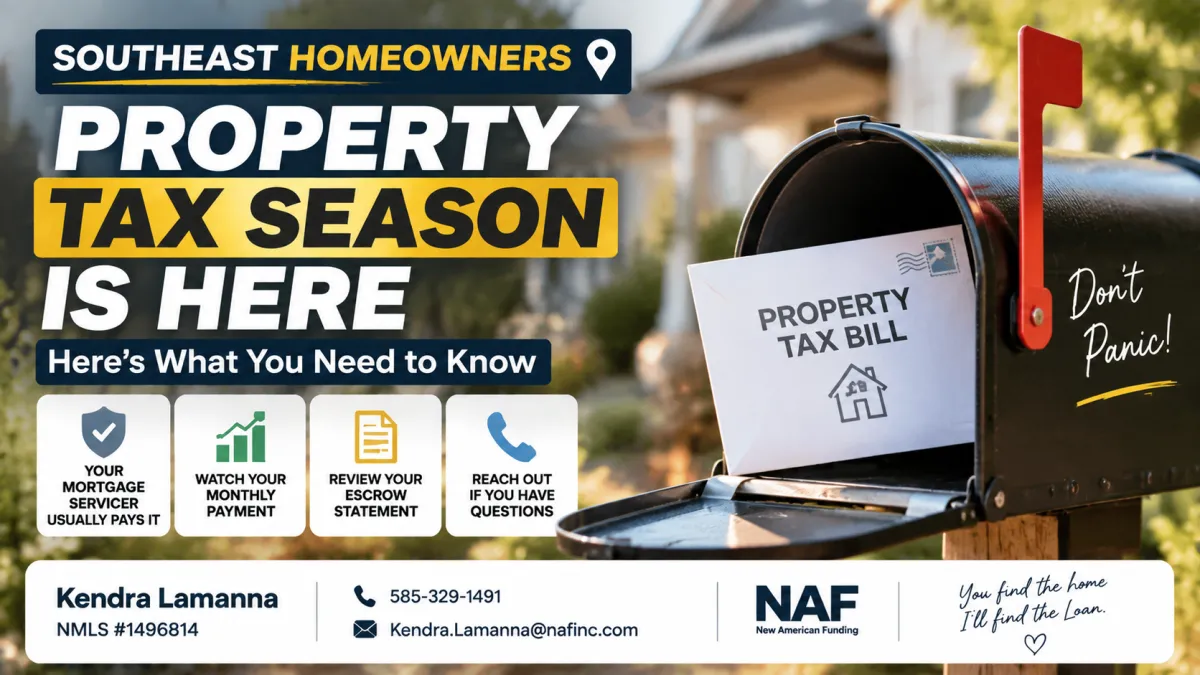
Southeast Homeowners Are Getting Property Tax Bills Right Now and Here Is What to Do With Them
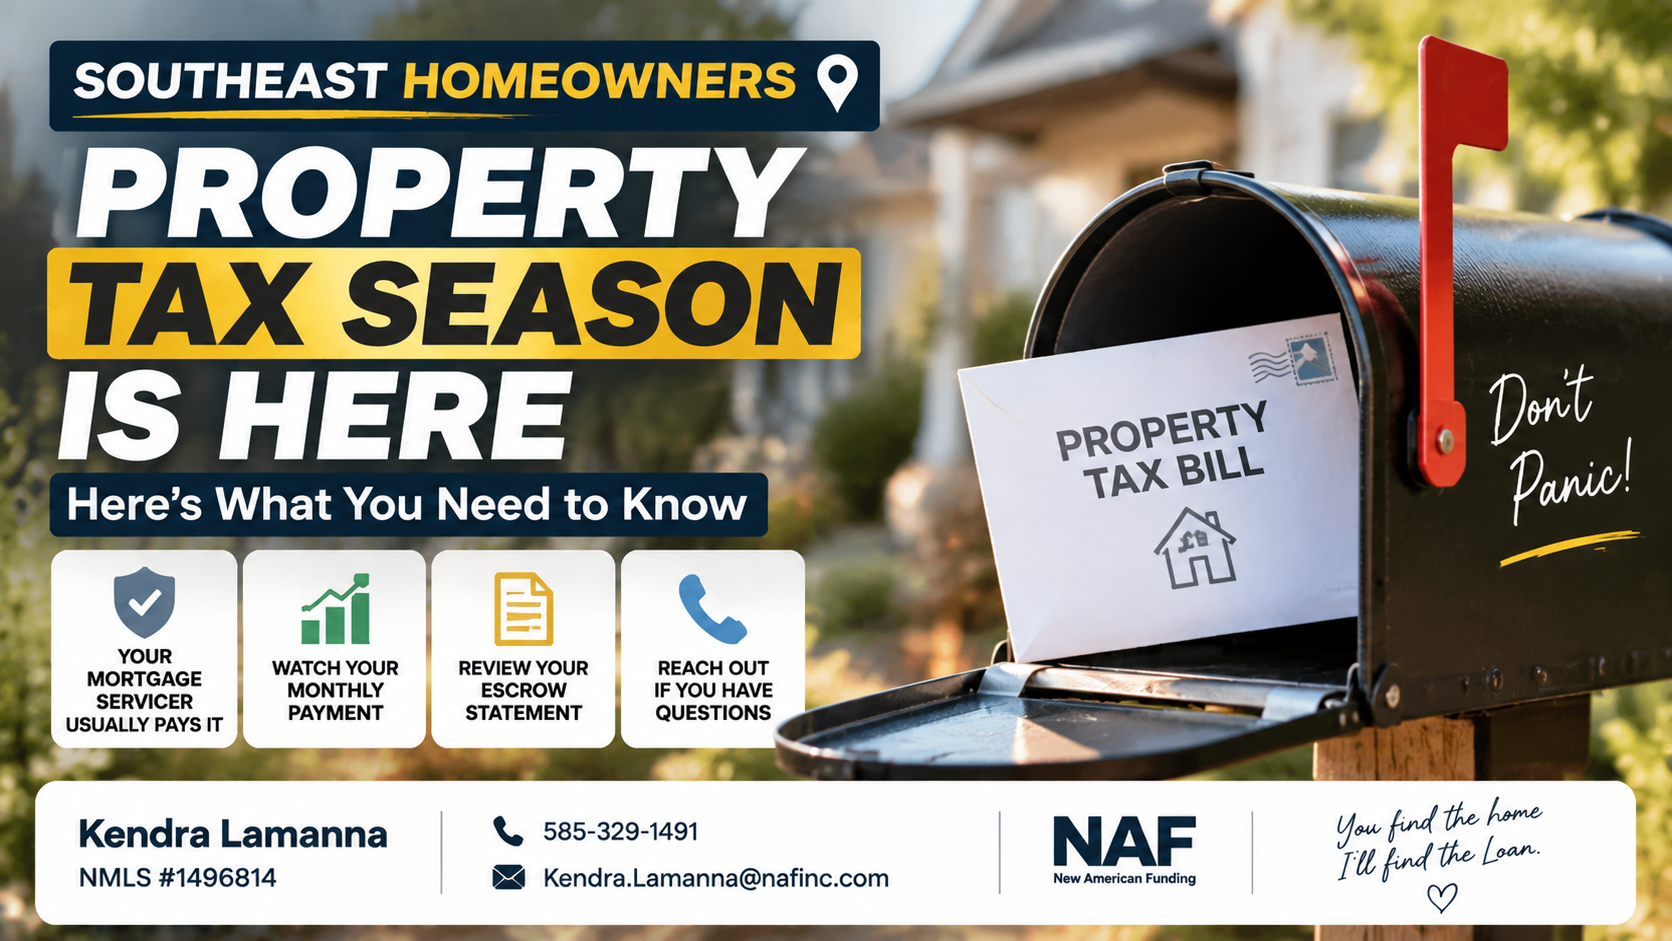
The Bill That Shows Up in the Mail and Causes Unnecessary Panic Every Year
If you are a homeowner in the southeast property tax bill season is here and that means a lot of homeowners are opening their mailboxes and seeing a number that looks alarming. Kendra LaManna at New American Funding wants to give you a quick heads up before that bill arrives so you know exactly what to do with it.
The Short Answer: Do Not Panic
If you pay your property taxes through your mortgage escrow account you do not need to write a check for that bill. Your mortgage servicer is already collecting a portion of your estimated annual tax obligation every month as part of your regular mortgage payment. When the tax bill comes due your servicer handles the payment directly from the escrow account on your behalf.
The bill showing up in your mailbox is informational. It is not a demand for payment from you personally as long as your taxes are escrowed through your mortgage. Hold onto it but do not write a check to the tax authority directly.
What to Actually Pay Attention To
Here is where Kendra's advice goes beyond the basics. Watch your monthly mortgage payment closely because the property tax bill season often coincides with or triggers an escrow review by your servicer.
If your actual tax bill came in higher than what your servicer was collecting for you may have an escrow shortage. That shortage typically gets spread across your next twelve monthly payments as a slightly higher payment amount until the account is balanced again.
If your actual tax bill came in lower than projected you may have an escrow surplus. In that case you might receive a refund check from your servicer or see a reduction in your monthly escrow contribution going forward. Small wins as Kendra puts it but real money worth paying attention to.
What to Do With the Escrow Statement
When you receive an escrow analysis statement from your mortgage servicer do not throw it to the side. This document explains exactly how your escrow account is performing, what your servicer expects to pay out in taxes and insurance over the coming year, and what your adjusted monthly payment will be if a change is needed. It is one of the most useful pieces of mail a homeowner receives and one of the most commonly ignored.
If you read it and have no idea what it means that is completely fine. Reach out to your current mortgage servicer for an explanation or contact Kendra LaManna directly. She is happy to walk through it with you and help you understand what the numbers mean for your monthly budget.
NMLS 1496814. Call or text 585-329-1491 or email [email protected].
Sources
ConsumerFinancialProtectionBureau.gov
FannieMae.com
MortgageNewsDaily.com
Investopedia.com
HUD.gov

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

Social Media Links
YouTube
Contact Us
(585) 329-1491
6000 Fairview Road, SouthPark Towers, Suite 1200, Office 1207 Charlotte, North Carolina 28210
